Moving to assisted living does not necessarily mean selling a longtime house. For families wondering how to pay for assisted living without selling a house, several financial strategies may make it possible to keep the property while covering monthly expenses.
That flexibility can matter when a house has financial or emotional value. Whether you hope to rent the property, preserve it for family, or simply avoid making two major decisions at once, exploring your options can make the transition more manageable.
Use Rental Income to Help Cover Assisted Living Costs
Renting out a house can create monthly income that helps offset assisted living expenses without giving up ownership. This approach may be especially useful when the mortgage is paid off or the expected rent can cover a meaningful portion of monthly expenses.
Families who do not want to manage a rental themselves can consider a property management company. Depending on the provider, services may include:
- Finding and screening tenants
- Collecting rent
- Coordinating repairs and routine maintenance
- Handling day-to-day tenant communication
Property management comes with an added expense, so compare those costs with expected rental income. A tax or financial professional can also explain how rental income, expenses, and deductions could affect your finances.
Consider a Home Equity Line of Credit
A home equity line of credit, or HELOC, is another option for financing assisted living while keeping a home. It allows a homeowner to borrow against available home equity rather than selling the property.
Unlike a lump-sum loan, a HELOC generally provides access to funds as they are needed. That flexibility may help families cover changing monthly expenses without borrowing the full available amount at once.
Because the house serves as collateral and repayment is required, review the interest rate, repayment terms, fees, and potential risks carefully. Understanding those details is an important part of keeping a house while in assisted living.
Explore Whether a Reverse Mortgage Is an Option
For eligible homeowners, a reverse mortgage may offer another way to access home equity. Depending on the type of reverse mortgage and eligibility requirements, funds may be available through options such as:
- Monthly payments
- A lump-sum payment
- A line of credit
Reverse mortgages have specific occupancy, repayment, fee, and eligibility requirements. Before making a decision, talk with a qualified financial professional or approved housing counselor about whether this approach fits your circumstances.
For families researching how to afford senior care without selling property, one important step is understanding both the immediate benefits and the long-term effect on the homeowner and their heirs.
Review Long-Term Care Insurance Benefits
Long-term care insurance may help cover qualifying assisted living expenses. If you or a loved one already has a policy, review its requirements before assuming what it will pay.
Look closely at details such as benefit amounts, covered services, elimination periods, and the length of coverage. Contact the insurance provider directly to learn what documentation is needed to make a claim.
Even when a policy does not cover the entire monthly cost, benefits may reduce the amount that needs to come from savings, income, or other resources.
Combine Savings With Other Payment Strategies
There is no single financial approach that works for every family. Personal savings, retirement income, investments, rental income, insurance benefits, and other resources may sometimes be combined to create a workable plan.
When comparing assisted living payment options without a home sale, consider both current expenses and what you may need later. A financial planner or tax professional can help you evaluate withdrawals and possible tax consequences before making changes to retirement or investment accounts.
This broader approach can also help families compare alternative ways to pay for assisted living instead of relying entirely on one asset.
Factor Assisted Living Services Into Your Budget
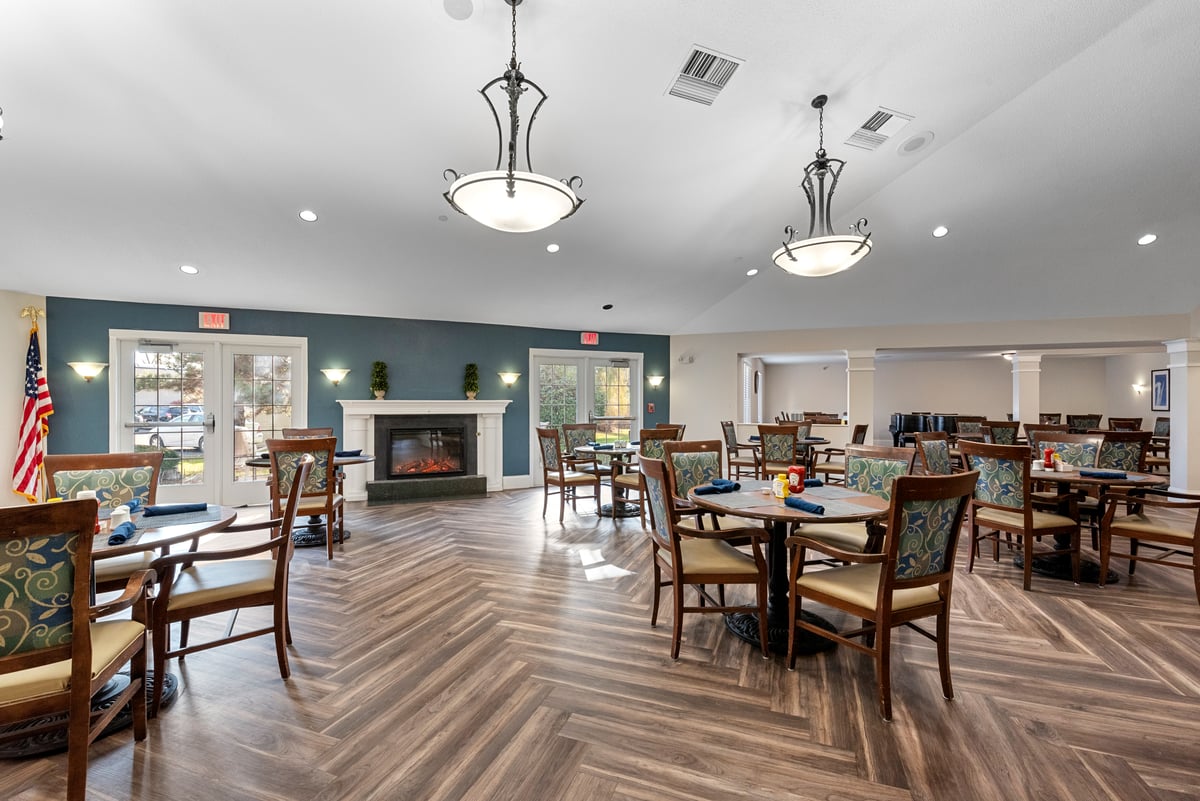
Understanding what is included in a community's pricing can make financial planning more accurate. LakeHouse New Holstein offers Assisted Living in New Holstein, Wisconsin, with one-bedroom and suite apartment homes. Residents also have access to weekly housekeeping and laundry services, freshly prepared meals, scheduled transportation, programs and outings, and support with personalized daily routines.
When comparing the cost of remaining in a house with moving to senior living, look beyond the monthly housing payment. Expenses for groceries, home maintenance, utilities, transportation, housekeeping, and other services can help provide a fuller comparison.
Families can also explore floor plans and pricing and review the community's amenities and services to better understand what may be included. LakeHouse New Holstein's amenities include landscaped outdoor spaces, a library, resident lounges, a fitness center, a salon and barbershop, and scheduled transportation.
Make a Plan That Fits Your Family
Keeping a longtime house while moving to assisted living can be possible, but the right strategy depends on your finances, property, goals, and eligibility for different funding sources. Comparing rental income, home equity options, insurance benefits, savings, and other resources can help you understand your choices before making a decision.
For families exploring LakeHouse New Holstein, understanding both the financial picture and daily experience can make planning easier.
Schedule a tour of LakeHouse New Holstein to explore the community, ask questions, and learn more about Assisted Living options.